Bitcoin Whales Add 47,000 BTC as Demand Falls to 2025 Low
Bitcoin whales added about 47,000 BTC during the sell-off, but wallets holding 10 to 1,000 BTC shed 64,900 BTC as 30-day apparent demand fell to its weakest level since April 2025.
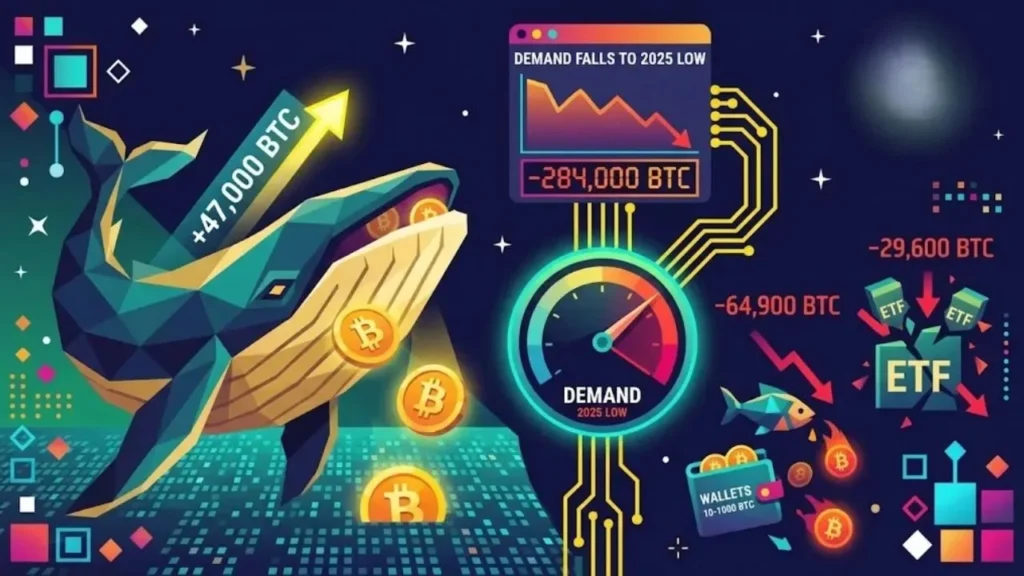
Bitcoin’s largest wallet group added roughly 47,000 BTC during the latest sell-off, but the buying has not been enough to offset withdrawals by mid-sized holders, weakening demand and persistent selling through US spot exchange-traded funds. CryptoQuant data shows wallets holding at least 1,000 BTC increased their balances while wallets holding between 10 and 1,000 BTC shed a combined 64,900 BTC.
The split helps explain why whale accumulation has not stopped the decline. Bitcoin’s 30-day apparent-demand reading fell to about minus 284,000 BTC, its weakest level since April 2025. The market is seeing large wallets add coins while demand from other groups contracts.
“What Donald Trump giveth, Donald Trump taketh away.”Paradigm’s Justin Slaughter (@JBSDC) joins @RebeccaRettig1 and @renato_mariotti on this week’s @CoinDesk Policy Protocol to break down the blue wave, Nvidia and export controls, and whether crypto legislation can survive a Democratic Senate. Person of the Week: Stacey Cunningham.Chapters / Timecodes 00:00 Welcome to The Policy Protocol 00:33 Breaking: Jensen Huang Resigns as Nvidia CEO 01:54 Do We Need a National AI Regulator? 02:28 Senate Tea: An AI Committee for Sherrod Brown? 02:53 Hot Topic: Can the CFTC Stop Exchanges From Blocking States? 05:48 Hot Topic: Swarm Riders and ‘Accountability Arbitrage’ 08:44 Guest: Justin Slaughter of Paradigm 09:20 The Blue Wave: ‘Trump Giveth, Trump Taketh Away’ 11:11 Export Controls and Nvidia’s Reckoning 12:04 How Durable Is Trump-Era Crypto Guidance? 13:03 Sue and Settle & the Congressional Review Act 14:32 Pared-Down Commissions and the Funding Question 15:39 Why We Won’t Get New Commissioners 17:31 The Real Funding Fear: A Government Shutdown 18:38 Can Crypto Legislation Survive a Democratic Senate? 19:25 ‘85% of CLARITY Is Fine’ 20:38 Waters vs. Warren: ‘An Ocean of Difference’ 21:07 Why Crypto’s Fate Comes Down to Age 22:32 ‘Progress Occurs One Funeral at a Time’ 23:28 Debrief: Crypto Goes Mainstream 24:09 Person of the Week: Stacey Cunningham 25:16 See You Next Week
— CoinDesk (@CoinDesk) November 14, 2026
Wallets holding at least 1,000 BTC added 47,000 coins
Data reported by TokenPost on November 14 shows that addresses holding more than 1,000 BTC added around 47,000 BTC during a decline of roughly 24%. Wallets in the 1,000-to-10,000 BTC range accounted for about 43,700 BTC of that increase.
The movement went the other way among smaller balance groups. Wallets holding 100 to 1,000 BTC reduced their balances by approximately 50,500 BTC. Those holding 10 to 100 BTC shed another 14,400 BTC. Together, those two groups cut their balances by about 64,900 BTC, more than the amount added by wallets above the 1,000 BTC threshold.
These figures describe changes in wallet balances. They do not prove that every coin was bought on the open market during the period. Blockchain data identifies addresses and their balances, not always the person or institution controlling them. Exchange custody movements, wallet reorganizations and transfers between addresses can affect balance-band data. The figures are a useful view of how supply is distributed, but they are not a complete record of investor intentions.
Bitcoin’s apparent demand has fallen to its weakest level since April 2025
The wider demand measure is more concerning. CryptoQuant’s November 10 market research had already warned that apparent demand was contracting at its fastest pace since March 2025. The latest reading fell to approximately minus 284,000 BTC. A negative reading indicates that estimated demand is running below the amount of new supply entering the market under the metric’s methodology. The latest level is the weakest since April 2025.
The same research also pointed to weak US spot demand, with the Coinbase Premium Index negative throughout the previous 30 days. That suggests US-based spot buyers were not providing the support seen during stronger recovery periods.
The demand measure is not a count of buy orders or a direct tally of coins purchased by investors. It is an on-chain estimate. Its value comes from comparing the trend with other signals, including ETF flows, exchange activity and realized gains or losses.
Spot Bitcoin ETFs have turned from buyers into sellers
US spot Bitcoin ETFs have also shifted in the wrong direction. The CryptoQuant figures cited in the November 14 report show the ETF flow measure moving from net inflows of about 49,700 BTC to net outflows of roughly 29,600 BTC. That reversal removes a source of demand that had helped absorb available Bitcoin supply.
ETF flows matter because creations and redemptions reflect changes in investor exposure through regulated funds. Sustained redemptions can add pressure when the funds sell or deliver Bitcoin to meet withdrawals. The figures should be read alongside the broader market, since ETF flows are only one part of spot demand.
ChainAIWire has tracked the recent reversal in Bitcoin ETF outflows and the pressure on BTC after US inflation data in its earlier Bitcoin market coverage.
Realized losses show how much selling is happening at a loss
CryptoQuant’s figures show net realized losses on 14 of the 16 days from October 29 through November 13, adding up to about 84,000 BTC. On November 13, realized losses reached approximately 18,500 BTC, the largest single-day total of the current downturn.
Realized losses occur when coins move on-chain at prices below the levels at which they were previously acquired, according to the metric’s calculation. A sharp rise can indicate that holders are accepting losses rather than waiting for a recovery. It does not mean every coin transferred was sold on an exchange, but it shows that loss-taking has become widespread among the coins being measured.
Bitcoin touched $65,000 on November 14, extending a decline of about 24% in the period covered by the wallet analysis. The move followed a series of lower prices that ChainAIWire covered in its report on Bitcoin falling below its 50-week average. Earlier coverage also examined the factors behind Bitcoin’s market decline.
Why whale accumulation has not stopped the decline
Large holders can absorb some of the Bitcoin being sold, but their accumulation does not guarantee that the market has found a floor. The amount added by wallets above 1,000 BTC was smaller than the combined reduction among wallets holding 10 to 1,000 BTC. At the same time, ETF flows and the apparent-demand measure point to weaker participation beyond the largest wallet group.
The distinction is between accumulation by one balance group and demand across the market. If short-term holders continue realizing losses, ETF investors keep redeeming shares and US spot demand remains weak, large-wallet buying may be insufficient to reverse the trend. A durable recovery would need broader spot demand to return, not simply a rise in balances among the largest addresses.
For now, the data supports two conclusions: large Bitcoin wallets have been adding coins during the decline, and demand across other parts of the market has weakened sharply. Whether those holders are buying a discount or accumulating ahead of further losses cannot be determined from wallet balances alone. The next readings on apparent demand, ETF flows and realized losses will show whether the gap is beginning to close.